Industry
Financial Services Marketing Automation Built for Compliance
Review
We build financial services marketing automation for banks, credit unions, lenders and fintech companies. Typical journeys welcome new account holders, encourage use of key services and offer the next product a customer may qualify for. Every message passes through your compliance team before it goes live. The workflow keeps a record of what was approved and sent.
Price
In your free proposal
Based on your goals and scope
Part of
Proposal
Free
Plan and price in writing
Journeys for new and existing account holders
The first months after an account opens shape how much a customer uses it. Most of our work starts there.
- New account onboarding – Prompts to activate a debit card, set up direct deposit, enroll in e-statements and download the mobile app.
- Application follow-up – Reminders for unfinished applications, written without exposing personal details in the message.
- Cross-sell journeys – Offers for auto loans, credit cards or home equity, based on eligibility rules your compliance and credit teams approve.
- Maturity and renewal reminders – Notices before CDs mature or promotional rates end.
- Loan milestone updates – Status messages through the lending process, kept separate from marketing.
- Surveys and feedback – Post-visit and post-closing surveys, with negative responses routed to staff.
Marketing automation for banks and credit unions
Bank and credit union data usually lives in a core system from a provider such as Fiserv, FIS or Jack Henry. A digital banking platform and a CRM hold the rest. Marketing platforms rarely connect to the core directly. We usually work from scheduled data extracts or a data warehouse, with only the fields each journey needs.
Salesforce Financial Services Cloud is a common CRM for larger institutions. Smaller institutions often use a CRM built for banking or a general platform. Either way, we map data flows in writing so your information security and vendor management teams can review them.
The Gramm-Leach-Bliley Act governs how you share customers' nonpublic personal information and requires privacy notices. We confirm vendor contracts and data flows with your compliance team before any customer data moves.
Disclosures, fair lending and recordkeeping
Financial ads carry specific disclosure rules. Under Regulation Z, certain trigger terms in credit ads, such as a payment amount, require additional disclosures. Under Regulation DD, deposit ads that state a rate must state the annual percentage yield. FDIC-insured banks and NCUA-insured credit unions also have rules on their official advertising statements.
Fair lending rules apply to who receives an offer as well as what it says. Targeting and eligibility rules should be reviewed by compliance, and Meta and Google both restrict targeting options for credit ads.
We build approval into the workflow. Each template keeps a version history, an approver name and an approval date. If you also have broker-dealer or investment adviser affiliates, SEC and FINRA rules require keeping records of business communications. Our financial advisor marketing automation page covers those rules in more detail.
Where AI fits and where it stays out
AI can draft copy variations for compliance to review. It can summarize survey comments, classify inbound messages and suggest which approved journey a customer should enter.
It should not decide credit eligibility, pricing or who receives a credit offer, unless that model has gone through your institution's model risk review. Banks typically bring AI tools under their model risk and third-party risk programs. We support that review with documentation of what each AI step does and what data it sees.
No AI-written message reaches a customer without human review. We log every AI step, so your auditors can see what happened and when.
Pricing, scope and reporting
You get a clear price in your free proposal, after we look at your goals. Cost depends on data integration, the number of journeys and how many review rounds your compliance process needs. Platform fees are billed by each vendor.
We will not promise deposit growth, loan volume or cost savings. We report service activation, product adoption, survey response and opt-out rates against your baseline.
We often work in Salesforce Marketing Cloud and connect it with your CRM through our CRM implementation team. For email content and design, see our financial services email marketing team. Browse all our AI automation services.
Last updated:
Case studies
Our work in this industry
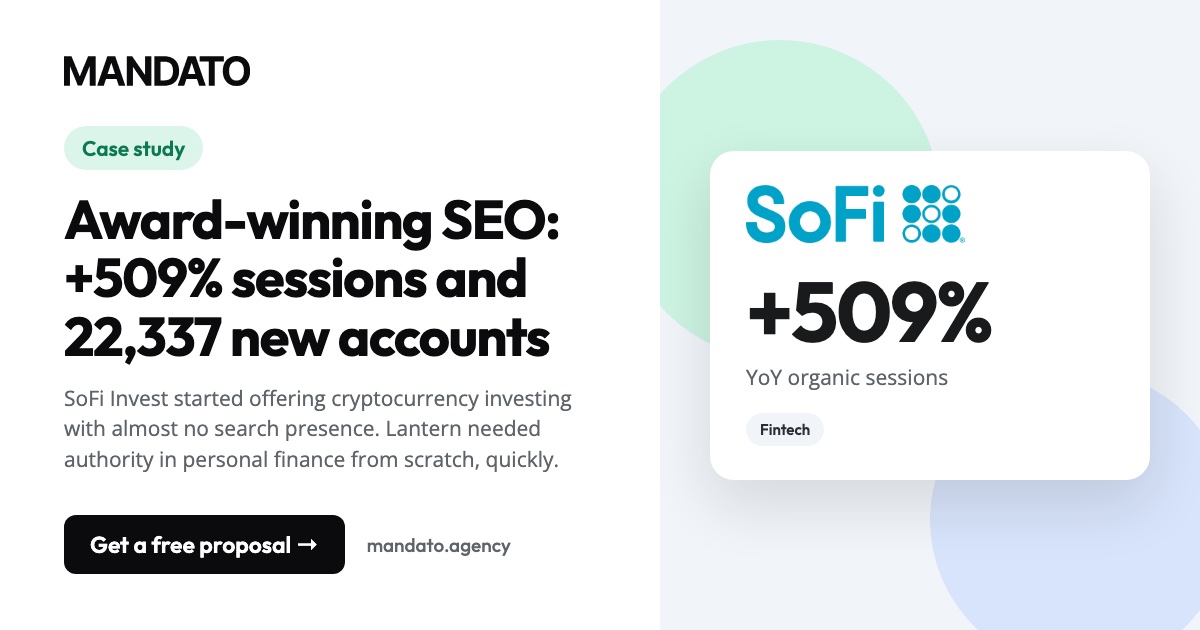
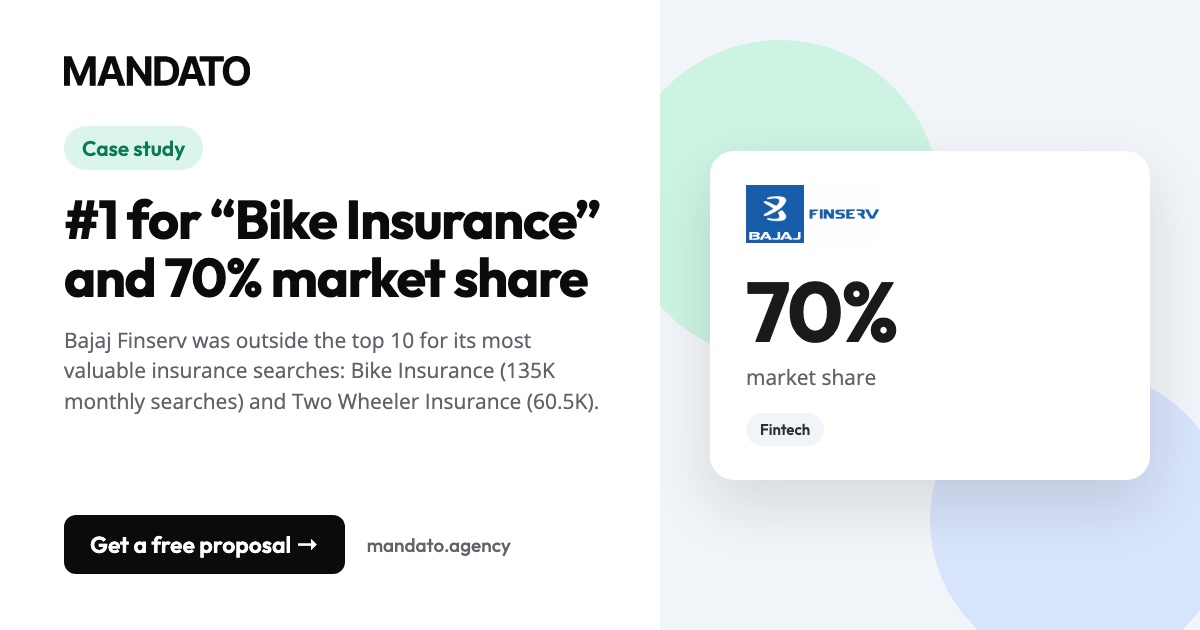
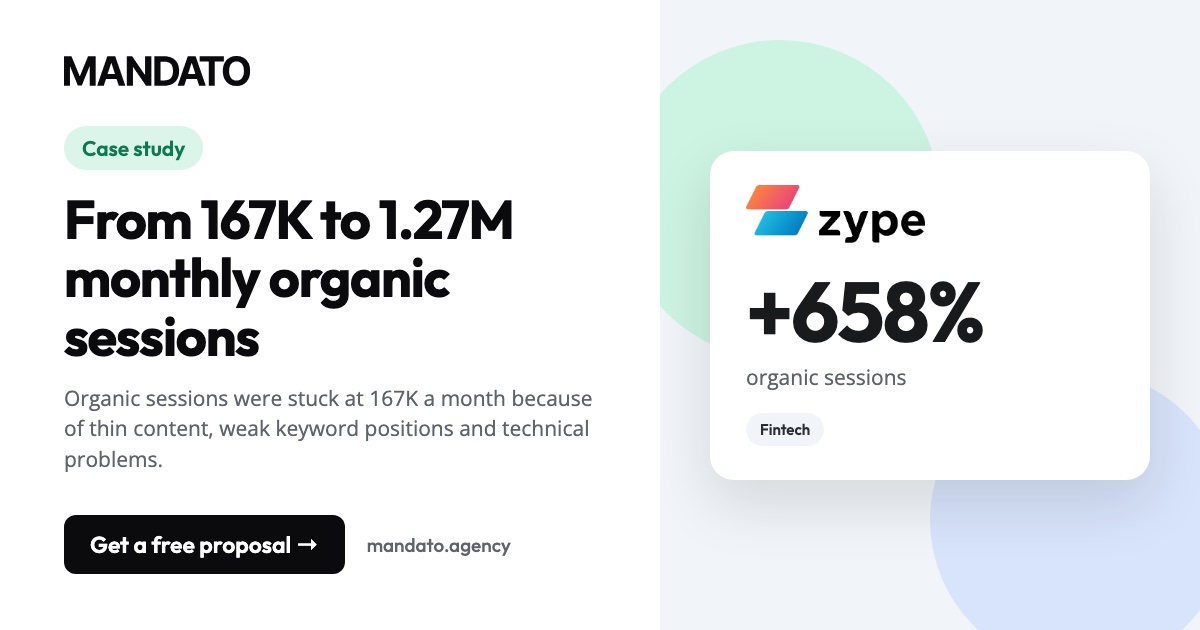
Results for fintech clients. They come from our other services, not this exact one.



FAQ
Financial Services Marketing Automation: questions
Usually through scheduled extracts or a data warehouse rather than a direct connection. Your IT team controls what data leaves the core. We define the fields each journey needs and nothing more.
We plan review rounds into the project from the start. Templates go to compliance in batches with notes on disclosures and targeting. Approved versions are logged before launch.
Yes. Credit unions use the same types of journeys, with member language and NCUA advertising rules. Field of membership rules can also shape who is eligible for an offer.
Yes, but some rate and account notices are required disclosures with their own rules. We separate required notices from marketing messages and let your compliance team set the wording.
Often, yes. Fintechs that partner with banks usually follow the bank's compliance requirements for marketing. We build the same approval and recordkeeping steps.
Related services
Get a free Financial Services Marketing Automation proposal
Tell us about your business and goals. We'll reply with a plan and a price.